Rental Property Cash Reserves: Plan for Vacancy, Repairs, and Replacements

A rental can look profitable in a normal month and still be difficult to own when rent stops or a major component fails. A reserve plan asks a different question from “Does the rent cover the mortgage?” It asks whether you can keep meeting obligations while dealing with an interruption. Start with the property, its condition, and its actual bills rather than a universal percentage.

This guide presents a planning framework with hypothetical figures. It does not establish a lender’s minimum reserve requirement or tell you how much cash your specific investment needs. Financing, leases, deposit rules, insurance, and tax treatment require their own review.

Separate three purposes for cash

Operating cash pays the bills you expect soon. A disruption reserve supports the property when income stops or an unexpected expense arrives. A replacement fund accumulates toward larger items that are not monthly expenses but are still foreseeable. You can track these purposes in one accounting system without pretending the same dollar can fund all three at once.

The CFPB’s property-budget guidance highlights costs beyond principal and interest, including taxes, insurance, association fees, maintenance, repairs, and utilities. Although that resource addresses homebuyers rather than setting investor reserves, its expense categories are a useful reminder: a mortgage payment is not the complete cost of ownership.

Write down the bills that continue without rent

Use recent statements and agreements to identify the payments that would remain if the unit were vacant. Include financing, taxes and insurance, required association payments, and utilities you would need to maintain. Separate amounts already collected through mortgage escrow from bills paid directly so you do not count the same cost twice.

Keep tenant deposits and other restricted or refundable amounts out of the owner’s available-reserve calculation. Check the local rules governing how those funds must be held and returned. A balance visible in an account is not automatically money available for a repair.

Stress-test a vacancy instead of guessing a percentage

Hypothetical property: monthly principal and interest are $1,250; taxes and insurance, not included in that payment, are $400; association charges are $150; and owner-paid utilities during vacancy are $100. That creates $1,900 of monthly carrying costs before repairs and other obligations.

A two-month vacancy would therefore require $3,800 for those listed costs. Add a hypothetical $1,500 turnover estimate and a separate $2,000 repair scenario, and the combined stress case becomes $7,300. This is not a recommendation that every rental needs $7,300. It shows how to connect assumptions to a cash requirement. Legal costs, deductibles, leasing charges, or a longer vacancy would change the result.

Do not count the missing rent again as an additional cash payment in that calculation. The stress case already assumes no rent arrives. If you also measure lost revenue for performance reporting, keep that separate from the cash needed to pay bills. Mixing the two can inflate the reserve estimate without making the plan clearer.

Build a replacement schedule from condition and quotes

List major components such as the roof, heating and cooling equipment, water heater, and appliances. Record condition, inspection information, a realistic replacement estimate, and the earliest plausible timing. A generic useful-life chart is not an inspection of your building. Where the decision matters, obtain a qualified assessment and current quotes.

Suppose a hypothetical replacement is expected to cost $9,000 in three years and you have already earmarked $1,800. Ignoring interest and cost changes, the remaining $7,200 divided by 36 months requires $200 per month. If the same replacement becomes necessary in 18 months, the contribution doubles to $400. The exercise makes timing visible; it does not establish the equipment’s life or future price.

Update the contribution when quotes or condition change. Also check whether your disruption scenario already includes that particular replacement. Either allow for a different unexpected repair or explicitly model simultaneous events. Do not double-count an identical expense just because it appears under two labels.

Distinguish lender reserves from your operating plan

Fannie Mae’s reserve guidance illustrates that underwriting requirements depend on the loan and borrower circumstances. Those eligibility requirements answer a lender’s question. Your operating model answers whether you can handle the property’s actual interruptions. Meeting a financing minimum does not, by itself, validate your vacancy assumption or repair estimate.

For several properties, test whether two problems could occur together. A portfolio in one geographic area can share exposure to the same weather event or local disruption. Rather than assuming every property’s reserve can support every other property simultaneously, write down which cash is committed and which is genuinely available across the portfolio.

Keep reserve transfers separate from tax deductions

Moving money into a reserve account is a budgeting action, not proof of a deductible expense. The IRS explains rental income and expense treatment, including distinctions involving repairs, improvements, and depreciation. Your tax records and your cash plan serve different purposes. Keep invoices and ask a qualified tax professional how actual spending should be treated.

Also avoid describing the entire mortgage payment as a deductible operating expense. The cash plan includes what leaves the account; the tax return follows tax rules. You need both views, but combining their labels can produce misleading estimates of spendable cash and after-tax results.

A reserve review you can repeat

  • Reconcile available cash and remove restricted or refundable balances.
  • Update carrying costs using current bills, avoiding escrow double-counting.
  • Run a vacancy-and-repair scenario with clearly stated assumptions.
  • Review replacement quotes, timing, and monthly contributions.
  • Decide what must be replenished before taking an owner distribution.

Begin with one property and one realistic stress case. Then connect the result to your wider rental portfolio planning. For a broader introduction to property spending, see renovation budgeting, but replace any older general figures with current local quotes. A reserve plan is valuable because its assumptions are visible and reviewable—not because it produces a reassuring round number.

Educational information, not individualized investment, tax, insurance, lending, or legal advice. All dollar figures are hypothetical and exclude costs not expressly listed. Prepared with AI assistance; linked sources checked September 27, 2026.

Is Your Business Cash Fully FDIC-Insured? A Practical Account Check

A bank logo and a business account name are not enough to establish how much of your cash is insured. The useful questions are more specific: who legally owns the deposits, which insured bank holds them, and what other balances share the same coverage category? This checklist is for U.S. FDIC-insured bank deposits. It is not a recommendation to move money or a determination of your individual coverage.

1. Identify the bank, not just the brand

Start with the legal bank name on the account agreement. The FDIC’s BankFind Suite lets you look up institutions by name, website, location, or FDIC certificate number. Save the relevant institution details alongside your account inventory. A familiar app name is not a substitute for identifying the institution holding the deposits.

Make a simple inventory with one row per account: account nickname, legal owner, legal bank, last four account digits, balance, and purpose. Do not put full account numbers or login credentials in a casually shared worksheet. When two accounts appear under different brands, check whether the underlying bank is actually the same before treating the balances as separately insured.

2. Confirm the ownership category

According to the FDIC’s business-account guidance, qualifying corporations, partnerships, and unincorporated associations have coverage of up to $250,000 for their combined deposits at one insured bank. The business must meet the applicable formation and independent-activity requirements. Qualifying business deposits are separately insured from the owners’ personal deposits.

Calling an account “payroll,” “tax reserve,” or “operating cash” does not create a new insurance category. Nor does adding authorized signers. For a qualifying entity, those accounts at the same bank are generally added together. Do not confuse an account’s purpose with its legal owner.

A sole proprietorship works differently. The FDIC’s single-account guidance explains that a sole proprietor’s business deposits are combined with that owner’s other single-category deposits at the same bank. A doing-business-as name does not by itself create separate entity coverage. Other ownership categories have their own rules; this article does not calculate trust, joint, retirement, or credit-union coverage.

3. Add the balances before checking the limit

Hypothetical example: a properly formed operating LLC that qualifies for separate business coverage holds $180,000 in checking and $110,000 in savings at the same insured bank. Its combined deposit balance is $290,000. Under the standard business-category limit, $40,000 would be above the $250,000 coverage limit. Naming the savings account “future payroll” does not change that arithmetic. This example assumes no other deposits, accrued interest, or special arrangement affects the calculation.

For a different hypothetical case, a sole proprietor has $170,000 in a personal single-owner savings account and $120,000 in a sole-proprietor business checking account at the same bank. If both belong in the single-account category and there are no other relevant balances, the combined amount is also $290,000—not two independent $250,000 allowances. Confirm the actual ownership category rather than using this simplified example as an account-specific ruling.

Check peak balances, not just a quiet day’s screenshot. A customer payment or planned asset sale can change the picture. Put a reminder in your cash review to revisit the inventory when you open an account, change the entity structure, or receive an unusually large payment. The FDIC’s Your Insured Deposits guide explains the ownership categories and aggregation rules in more detail.

4. Treat fintech and payment-app balances as a separate check

The FDIC cautions that nonbank companies are not themselves FDIC-insured. Money sent through an intermediary may qualify for pass-through coverage only after deposit at an insured bank and satisfaction of applicable conditions, including ownership records. Deposit insurance does not cover the insolvency or bankruptcy of the nonbank intermediary.

Before relying on an app for operating cash, ask which bank holds the funds, when the deposit occurs, what records identify your ownership, and how you would obtain statements if the app became unavailable. Keep the agreement and contact details somewhere you can reach without logging into that same app. These are practical due-diligence questions, not a finding that any particular provider is unsafe.

5. Separate insurance coverage from payment continuity

“Insured” and “available for tomorrow’s payroll” are different questions. Build a small continuity checklist: who can access the account, how payments are approved, what happens if the usual approver is absent, and which support channel works if online access fails. Verify transfer limits and cutoffs directly with each provider instead of assuming all accounts behave the same way.

If you decide a second banking relationship would support operations, evaluate it as a business decision with fees, controls, and reconciliation requirements—not as an automatic solution. More accounts can mean more administrative work. Never break a payment into unfamiliar destinations merely because an email claims the bank details have changed; independently verify the instruction through a contact method already known to you.

The questions to take to your bank

  • What is the legal name and FDIC certificate number of the bank holding each deposit?
  • Which ownership category applies, and which balances must be combined?
  • Are any deposits placed through an intermediary or sweep arrangement, and how are they recorded?
  • What happens if our normal online access or payment-approval process is unavailable?
  • Who should review the calculation when our balances or account structure change?

Use the FDIC’s guidance and ask the bank or an FDIC deposit-insurance specialist about facts specific to your accounts. For the operating side of the decision, connect this review to your 13-week cash-flow forecast. A coverage inventory tells you where money is held; the forecast tells you when the business expects to need it.

General educational information, not individualized banking, investment, legal, or tax advice. Coverage depends on the actual account ownership and applicable requirements. Examples are hypothetical. Prepared with AI assistance; linked FDIC guidance checked September 27, 2026.

How to Build a 13-Week Cash-Flow Forecast for Your Small Business

How to Handle Cash Flow Problems

A profitable business can still face a bad cash week. An invoice may count toward revenue long before the customer pays, while payroll and rent arrive on fixed dates. A 13-week cash-flow forecast is a practical way to see those timing problems before they become urgent. It is a planning worksheet, not a prediction or a substitute for your financial statements.

The basic calculation is straightforward: opening available cash + expected cash received − expected cash paid = closing available cash. Government guidance on cash-flow forecasting uses this same opening-balance, inflow, outflow, and closing-balance structure. The weekly format below is a suggested management approach; the 13-week horizon is not a legal requirement or a guarantee that every risk will be captured.

Start with money you can actually use

Choose one starting date and reconcile the opening figure to your bank records. Exclude restricted funds and money held for someone else. Show committed payments clearly rather than treating every dollar on a banking dashboard as freely spendable. An undrawn credit line belongs in a separate financing section, not in your opening bank balance.

Use 13 columns, one for each week. Under each column, give receipts, operating payments, financing movements, and closing cash their own rows. Keep the first version simple enough that you can update it in one sitting. A detailed model nobody maintains is less useful than a short model with current assumptions.

Forecast receipts by collection date, not invoice date

Take each meaningful outstanding invoice and write down when you reasonably expect the money to arrive. A promised payment, a disputed invoice, and a proposal that has not been accepted should not receive the same confidence level. Put the customer, amount, expected date, and reason for the estimate in a notes column.

For card sales or marketplace revenue, model the cash settlement you expect to receive. Avoid counting gross sales once and the same processor payout again. Treat refunds, fees, reserves, and settlement delays consistently with your actual statements. When timing is uncertain, build a later-payment scenario rather than quietly assuming the best.

Make the payment calendar specific

List obligations in the week they are expected to leave the account. Do not spread a large quarterly payment evenly across three months if the money must leave all at once. Include owner distributions and debt principal payments even when their accounting treatment differs from an ordinary operating expense.

  • People: payroll, related payments, and agreed contractor invoices.
  • Operations: rent, utilities, subscriptions, insurance, inventory, and supplier payments.
  • Calendar items: taxes, renewals, deposits, equipment purchases, and seasonal commitments.
  • Financing: borrowing, interest, principal repayments, and owner contributions or withdrawals.

Your records should support these entries. The IRS recordkeeping guidance explains why businesses need records of income, expenses, and supporting documents. This forecast does not determine what is deductible or when a tax payment is legally due; obtain that information from your accountant and the applicable agency.

A worked example: the problem is week two

Hypothetical example—not a client result: a small service business begins with $30,000 of available cash. In week one it expects $18,000 of receipts and $22,000 of payments, leaving $26,000. In week two it expects $12,000 of receipts and $29,000 of payments, leaving $9,000. In week three it expects $28,000 of receipts and $20,000 of payments, leaving $17,000.

The three-week ending balance looks manageable, but it hides a dip. Suppose management has chosen a $15,000 planning floor based on its obligations and risk tolerance. Week two falls $6,000 below that floor. That is a signal to investigate now—not proof the business needs exactly $6,000 of borrowing. The floor is an assumption in this example, not a recommended minimum for every business.

Now stress-test a $10,000 customer payment expected in week two. If it slips into week four and nothing else changes, week two closes at negative $1,000. The business has learned something actionable: the collection date matters more than the attractive week-three total. Confirm the payment, evaluate discretionary spending, and discuss any financing or revised terms before an obligation is missed.

Use three scenarios, not false precision

Keep a base case, a slower-collections case, and a case with a plausible unexpected payment. Change a small number of assumptions so you can explain why the balances move. A downside scenario should identify decisions: which commitment can be delayed by agreement, which purchase can wait, and who owns the next customer follow-up. Never assume a tax, wage, or contractual obligation can simply be postponed.

Pay special attention to the lowest projected balance, the week it occurs, and the largest uncertain receipt. A forecast that depends on one unconfirmed sale deserves a different response from one supported by a broad set of reliable collections.

Turn the forecast into a weekly meeting

Replace last week’s estimates with actual receipts and payments. Record why material differences happened: a late customer, a missing invoice, an expense omitted from the model, or simply the wrong timing assumption. Then add a new thirteenth week. Keep the earlier version so you can distinguish a genuinely improving position from repeatedly moving an optimistic receipt forward.

End the review with three assignments: the most important collection action, the largest upcoming payment to verify, and the spending decision that depends on available cash. Give each one an owner and a date. The forecast becomes useful when it changes a decision, not when it produces a colorful spreadsheet.

Your next step

Build the first four weeks using actual bank balances, open invoices, and scheduled payments. Extend to 13 weeks only after the opening section makes sense. For background, read what cash flow means and ways to approach cash-flow problems. Use an appropriately qualified adviser when decisions involve borrowing, solvency, tax, or other legal obligations.

Educational information, not individualized financial, accounting, or legal advice. All numerical examples above are hypothetical. Prepared with AI assistance; the linked sources were checked during preparation on September 27, 2026.

Why a Cashless Society Works

Why a Cashless Society Works

Can you imagine living your life where you no longer need cash for your financial transactions? Sounds too good to be true? Well, it’s not.

Now more than ever, an increasing number of service companies, businesses, financial institutions, and even some governments are steadily and slowly moving towards the so-called cashless society. Yes, electronic transactions have become and will sooner become the new norm, and it’s not impossible to see why.

If you are wondering why a cashless society works, the answer is simple: it offers a lot of benefits. These include eliminating the challenges that come with managing currency and the costs involved with handling cash. If you have a business, you can also finance it cashless!

Still unconvinced? Continue reading to know more about a cashless society and all the perks that come with it.

Cashless Society Defined

To understand why a cashless society works, you should first learn how it works in the first place. A cashless society eliminates coin-based and cash paper currency and replaces them with electronic payment methods. These electronic transactions include the use of electronic payment services such as PayPal or Apple Pay, as well as debit or credit cards.

Available Payment Methods

Payments take place electronically in a cashless society. The following methods can be used when transacting with individuals, organizations, and other businesses.

  • Debit and credit cards

Debit and credit cards are among the most popular alternatives to cash you can simply tap or swipe to pay bills, transfer money, and make purchases.

  • Electronic payment apps

All you have to do is download the apps on your smartphone or other devices that serve as your mobile wallet. You can use these for B2B transactions and P2P payments.

  • Virtual currencies

Digital currencies or cryptocurrencies are utilized for money transfers and encourage competition to help lower the costs involved.

Perks of a Cashless Society

Among the top reasons why more and more countries are now shifting to a cashless society is mainly because it is very convenient and simple. As long as you have your card or phone with you, you can get instant access to all your cash holdings.

It also means you won’t have to bother visiting an ATM just to get cash or worry that you don’t have cash handy to buy something you need urgently.

Here are other benefits of a cashless society:

  • Automatic Paper Trails

Financial crimes including drug-related operations, illegal gambling, or money laundering would be more challenging in a cashless society. Such crimes often involve cash and don’t leave transaction records. In a cashless society, on the other hand, it will be easier to trace these crimes when the source of funds can be easily identified.

  • Cost Savings

Handling cash comes with a price. Printing bills and minting coins cost money. Businesses also have to deposit money and withdraw it once it runs out. They also need to work with companies for the safe transportation of cash. All in all, you need to spend resources and time to protect and transport large sums of money.

  • Easier Exchange of Currency

It can be a hassle to travel with cash, especially when you need to exchange dollars for local currency. With a cashless society, it saves you from the worries of the withdrawal amounts and local currency since the electronic devices will deal with the exchanges on your behalf.

Are you ready to go cashless soon?


What is an SBA Loan?

What is an SBA Loan?

If you are a small business owner, you already know the importance of financing not just when getting started but also as you grow your business. Unfortunately, small business loans with affordable terms are not always easy to find. This is where SBA loans can help.

SBA Loan Defined

An SBA loan is a business loan backed by the Small Business Administration. Instead of disbursing the loan itself, the SBA guarantees a maximum of 85% of the amount of the loan provided through a lender approved by the agency. These lenders are often non-profit lenders or banks.

With the backing of the SBA, the bank will more readily approve a small business for a loan that has a low down payment, long repayment term, and a reasonable interest rate.

These loans also come in various forms although the most popular ones include the ‎SBA 504/CDC loan, the SBA Microloan, and the SBA 7(a) loan. These loans can be used to buy equipment, add to working capital, expand your business, and more.

Benefits of SBA Loans

SBA loans are no doubt the most in-demand lending product for small businesses available on the market right now. This is because it is the ideal financial middle ground for owners of small businesses. Some programs even offer flexibility in how you will use the loan proceeds with the loans themselves secured as well.

Here are the top benefits of SBA loans:

    1. It’s meant for small businesses.

Banks are usually hesitant to fund small businesses since these are riskier bets compared to larger corporations. They also need extensive underwriting for smaller amounts of loans.

Online lenders, on the other hand, tend to have more relaxed requirements. They are also more willing to fund smaller and younger businesses with lower credit scores, often offering loan products with higher interest rates due to the assumed risk.

SBA loans are also a great middle-ground offering small businesses funding bank loan-type at affordable rates and encouraging repayment and growth.

    1. Funds can be used in different ways.

Several SBA loan programs implement various rules regarding the use of proceeds. But with an SBA ‎7(a) ‎program, for instance, a recipient will be able to use the loan for renovation and expansion, new construction, building or land purchase, as working capital, buy equipment, refinance debt for good reasons, and so much more.

Some programs let you finance purchases of long-term fixed assets., use the loan as a seasonal credit line, and others.

3. Loans are secured.

SBA loans often require collateral but nothing is wrong with this. It is almost impossible to look for an unsecured business loan, or one that doesn’t come with collateral, that has reasonable interest rates. With collateral in place, you can inform the bank of what you want to give as payment if you end up defaulting on the loan for whatever reason instead of just leaving things to them.

Thanks to SBA loans, small business owners can finally get the funds they need to grow and expand their ventures.


Top Five Careers for 2023

Top Five Careers for 2023

With the whole world finally back to normal, and with everyone returning to work, most people are either rethinking their careers or starting one for the very first time.

No matter which group you belong to, the following are the top five careers for 2023 that have been seeing a high demand across the globe.

Data Scientist

Just so you know, data is now the new gold, and this gold rush has led to the development of a job market that won’t go away any time soon. It only means that jobs related to data science will continue ruling this 2023. It is even revealed that data science jobs will remain relevant up to 2030.

But there might be a catch here. Some numerous jobs and roles fall under the umbrella of data science. This can make things a bit confusing for someone who wants to switch career streams or is just getting started.

Machine Learning Engineer

The demand for machine learning engineers has seen significant growth for the past few years. As an increasing number of companies look into machine learning to safeguard their businesses from potential disruptions in the future, the demand for these professionals is shooting up as well.

This is why there’s no doubt that it is one of the top five careers in 2023. And one of the best things about it is that there will be exponential growth in your career graph and you can even solve real-life issues.

Marketing Analyst

The responsibilities and roles of marketing analysts are an off-shoot of data science careers. These experts analyze data sets of market campaigns or segments and use these to generate usable insights.

This is also among those careers that require applicants who have business acumen and scientific knowledge at the same time. One of its biggest perks is that you can even work wherever you like, not to mention that you can also showcase your creativity.

Network Security

Cybercrimes have been estimated to have a global annual cost of $6 trillion. On top of that, cybercrimes also grew by over 600% since the start of the COVID-19 pandemic. What does it mean? It means that now is the perfect time for you to try a career in network security.

Network security experts maintain the security of the internal data of companies and their partners and clients. Since a high cost is at stake when a security breach occurs, this makes this career rather lucrative.

The scope for roles in the field of network security is also expected to grow in the near future, which means there is continuous learning and job security here.

Nurse Practitioner

Nurse practitioners are believed to be one of the most in-demand and top five careers in 2023. It is mainly because quality healthcare has now become one of the most valued professions not just these days but even in the future. Here, you have to become a certified nurse first and continue to hone and add to your skills. This career offers longevity and even the chance to work independently.


Top 5 Side Hustles for 2023

Top 5 Side Hustles for 2023

Side hustles are the hottest craze right now. There’s no surprise there at all. Considering the current economic condition, people are working harder than ever to keep up with the demands of life and make ends meet.

Whether you are looking for your next side hustle, or this is the first time you’ll try your luck with an extra stream of income, here are the top 5 side hustles for 2023 that you might want to check out and consider.

Freelance Bookkeeping

With a potential income of $20 to over $40 per hour, the major role of a freelance bookkeeper is to help business owners in managing and record their everyday financial transactions. These can include payment collection, payroll management, and bill payments.

Bookkeeping is different from accounting, and you can even begin bookkeeping online without a certification or degree. But as a bookkeeper, you should familiarize yourself with financial software programs and balance sheet reading and creation.

You can also work online and receive your payment either weekly or daily. if you’re good with numbers, this one’s the best side hustle for you.

Food Delivery

Food delivery services have gotten busier than ever. Thanks to the massive growth of these services, most of them need more drivers who can expect earnings of $20 to $25 per hour these days.

Food delivery drivers can often schedule when to drive any time they want. Typically, there are also no limits or minimums to the number of hours they can work per week. If you love to drive and you are also a certified foodie, why not become a food delivery rider?

Freelance Writer

Freelance writing has gotten broader than ever, and now encompasses several jobs which include blog posts, ghostwriting, catalog descriptions, print and online articles, and email newsletters. Some also specialize in web copy, content mills, technical writing, grant writing, resumes, and marketing campaigns.

Freelance writers can earn $500 to $5,000 per month although remember that it might take some time to build and grow your business and portfolio.

Blogging

Successful blogs can generate $10,000 up to a staggering $200,000 a month in revenues from ads and affiliates. You get paid every time readers click the links on your blogs to try a particular service or product.

And believe it or not, some bloggers didn’t even launch their blogs for the sake of making money alone. For most bloggers, it‘s because of their passion for writing. But the moment their blog started generating revenue, things got bigger from there.

Copyediting or Proofreading

Rounding up the list of the top five side hustles for 2023 is none other than copyediting or proofreading. Businesses, websites, and bloggers all need proofreaders, and most of them pay well for such services.

To make things even better, you can start your side hustle with just your laptop no matter where you are in the world. You can even set your rates and charge your clients per hour. Copyreaders or proofreaders can earn $1,000 to $20,000 per month.

Which of these side hustles would you like to try this 2023?


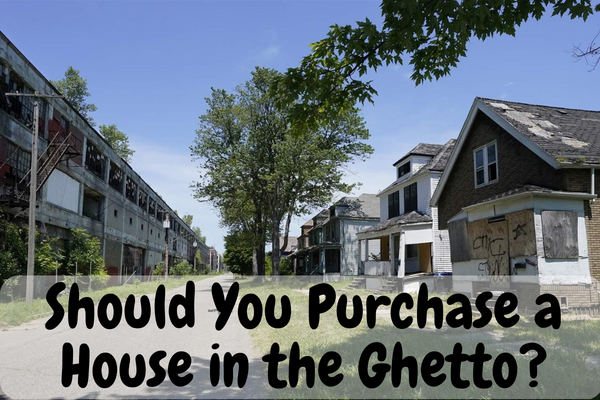
Should You Purchase a House in the Ghetto?

Should You Purchase a House in the Ghetto?

Ask any real estate investor, and they will surely tell you that the path isn’t always filled with roses. Most of the time, they face major dilemmas at least once or even a few times throughout their careers.

Imagine this: you found a lovely property with excellent value. But what if its location is far from ideal? What if there are high crime rates or the nearby houses in the neighborhood are rundown? What if it’s in the ghetto?

Should you purchase a house in the ghetto in the first place? Would it be worth the risk?

Location Always Makes a Big Difference

This dilemma is perfectly understandable and even common. As they always say in the world of real estate, location is the most important word in the field. But as expected, successful investments in real estate is never as straightforward as that.

Some investors do thrive in lower-end or poor markets, but others try to stay away from sketchy neighborhoods as much as possible. At the end of the day, it ultimately boils down to professional experience and personal preference. It means that you will be the one to determine if the potential rewards will be worth the risks or not.

The Good

Before anything else, your success will ultimately depend on what you plan to do with the house itself. If you feel confident about buying the property, giving it some fixes and repairs, and flipping it as fast as possible to make some profit, then, chances are you won’t be facing a lot of risks.

If you plan to buy the house, renovate it, and rent it out, you need to consider more things before you make your final decision.

Even a nice property in the ghetto will possibly come with a cheap price tag, and this happens to be one of the best appeals of investing in this particular market. You will have an easier time paying off your mortgage, property taxes, and other costs involved with home ownership.

Most importantly, buying a house in the ghetto can also help grow your rental portfolio. As long as you do it right, you can also expect high ROI or returns on investment.

The Bad

Just like anything else in the world, nothing ever comes without a negative side. For starters, houses in the ghetto tend to have lower rent or resale prices. The higher risk of crimes can also affect the cost of your insurance. And if the neighborhood you choose has a downward trend, you might end up dealing with poor or no ROI at all.

Study and Monitor the Trends

Just like other real estate investments, it would always work to your advantage if you consider and factor in the past, present, and future of the specific neighborhood where you plan to buy. For all you know, even if it looks a bit run-down today, positive community initiatives or gentrification may soon help it up.

It means you can purchase a house for a cheaper price and later on, it might see a drastic increase in appeal and value as the neighborhood becomes more in demand and desirable. You can even snatch up a few cheap properties that you can fix and attract more tenants that can revitalize the community down the road.


Should You Go to College When You’re an Entrepreneur?

Should You Go To College When Youre an Entrepreneur

Nothing is easy in this life, especially when major decisions are concerned. Even a single decision can have a major effect on your future. Just when you thought you made the right choice, you might end up realizing sooner than later that it was actually the wrong one.

If you’re already an entrepreneur, you might have second thoughts about going to college. Should you go to college when you’re an entrepreneur, then?

Since there is no way you can predict your future, you have to take a smarter approach before you decide for good. Take a look at the different possible scenarios so you can analyze your life and determine whether you should be going to college or not when you’re already an entrepreneur.

You’re in College or University Already and You’ll Graduate Soon

It won’t make sense to throw away your college degree only because you already have a business of your own. You can continue to hone and develop your business now even when you’re attending school.

You can even use this precious time to build more connections, double down on networking, and make friends in different fields. For all you know, you might even end up tapping into this particular network down the road.

You Won’t Incur Debt Thanks to Your Full Scholarship

If ever this is the case, it is recommended to use it for everything as much as possible. After all, not everyone is lucky enough to receive free education, so don’t miss the chance to take advantage of such a rare opportunity.

You’ve Been Accepted to a Topnotch College

There is no reason for you not to go, provided that the debt load won’t become a burden and that you won’t get strapped to a corporate job position for the rest of your life.

Studying in a top-notch college won’t only guarantee a high-quality education but it will also help you gain true expertise you probably won’t get anywhere else. Most importantly, you will also be able to build a stronger network that can benefit you throughout your life.

Going to college is also the perfect opportunity for you to study and master the art of networking. You can even consider it as your time to practice and test the waters. This is the kind of network that doesn’t come with a price.

Even the degree itself will be extremely valuable as well, especially if the time comes that you’ll need a regular job for whatever reason. There’s nothing wrong with having a backup plan in place. Again, while

The Bottom Line

Again, major life decisions like determining if you should still go to college or not when you’re already an entrepreneur are never easy. Although neither of these options will ruin or compromise your chances of becoming successful in your business, one thing is for sure: the choice you make will ultimately shape what will happen for the rest of your life. So, always choose wisely!

Is House Hacking a Real Thing?

Is House Hacking a Real Thing?

Hacks are ruling the world right now. From life hacks to more technical hacks, everyone’s going crazy about hacks that simplify things for them. But have you ever heard of the so-called house hacking?

Yes, there is such a thing as house hacking. It is a modern lifestyle choice inspired by old-school ways and re-imagined thanks to the latest home-sharing platforms.

What is House Hacking?

To put it simply, house hacking is all about looking for ways to make money out of your home. House hacking traditionally meant purchasing a multifamily property and living in one unit, while the rest is rented out. The rental payments will then go to the owner’s mortgage while the owner maintains the property and build equity on it.

Ask any savvy investor and they will surely tell you that multifamily properties and other similar properties are one of the easiest ways to master the ins and outs of being a landlord and property manager while enjoying the perks of their tenants paying for their housing expenses.

Why Try House Hacking?

House hacking is perfect for a temporary reduction of living expenses. it is also a great option if you are still testing out the waters of real estate investing. Either way, considering the exorbitant housing cost, house hacking is an effective method to use an existing asset to afford your lifestyle, set aside money for savings, or purchase more properties while building your home equity.

Popular House Hacking Strategies

Everyone can try their hands at the following house hacking strategies. All you have to do is find the one that suits you best:

  • ADUs

Renting an ADU or Accessory Dwelling Unit, also called the luxury house hack, is perfect if privacy matters the most to you or if you have a family. You can build an ADU in your backyard or buy a property with a readymade ADU.

  • Multifamily Property

Fourplexes, triplexes, and duplexes are the perfect examples of multi-unit properties. You will live in one unit with the rest rented out. People often apply for loans for these properties, particularly first-time home buyers.

It is a great house hacking strategy for markets with lower prices. However, profit may be difficult in expensive housing markets with rents that can’t even cover mortgage payments.

  • Short-Term Rental

As long as the county and homeowners’ association law allows it, any type of property can be transformed into short-term rentals. All you have to do is list the property on online platforms and have it rented out as often as you want. This house hacking strategy often generates positive ROI, especially in areas with high traffic.

  • Single-Family Rental

Buying a large single-family home is the easiest way to try your luck in house hacking. You just stay in one room and the rest is rented out. Just make sure that there is sufficient space in the common area and that there are enough bathrooms for a more comfortable experience for everyone.

Yes, house hacking is a real thing, and yes, you can also try it for yourself!